
High-interest debt acts like a leaking pipe in your home budget. Every single month, money drips out of your bank account and goes straight to bank interest. If you only make the minimum payments, that leak stays open for years. You end up paying back two or three times what you originally borrowed.
You need a clear plan to stop the leak. You need a system that attacks your debt using pure math.
That system is called the Debt Avalanche.
If you want to save the most money possible and become debt-free as fast as math allows, this method is for you. In this guide, you will learn exactly how the debt avalanche works, why it is so effective, and how to set up your own payoff map today.
What Is the Debt Avalanche Method?
The debt avalanche is a repayment strategy where you pay off your debts in order of interest rate. You start with the debt that carries the highest annual percentage rate (APR). You put all your extra money toward that single debt while paying the required minimums on everything else.
Once that highest-interest debt is completely gone, you take all the money you were sending to it and roll it over to the debt with the next highest interest rate.
Think of a small snowball rolling down a mountain. As it slides down, it picks up more snow and grows into a massive avalanche. In financial terms, every debt you eliminate frees up cash. That cash joins your monthly payment pool, creating a giant force that crushes the remaining balances faster and faster.
Debt Avalanche vs. Debt Snowball: What Is the Difference?
Before you build your map, it helps to understand how the avalanche method compares to its main alternative, the debt snowball.
-
The Debt Snowball targets your smallest balance first, regardless of the interest rate. It gives you fast mental wins because accounts close quickly. However, you pay more interest overall.
-
The Debt Avalanche targets your highest interest rate first, regardless of the balance size. It saves you the maximum amount of money and cuts down your total time in debt.
Here is a quick way to think about it: The snowball method targets your emotions. The avalanche method targets your bank account. If you care about keeping more of your hard-earned money away from credit card companies, the avalanche approach is the clear winner.
Step 1: List Every Debt You Owe
You cannot fix what you do not track. Your first step is to pull up all your account statements and write down four basic facts for every debt you have:
-
The lender name (e.g., Credit Card A, Personal Loan B, Car Loan)
-
The total balance (the exact amount you owe today)
-
The interest rate / APR (look for the percentage sign on your statement)
-
The minimum monthly payment (the lowest amount you must pay to stay current)
Do not leave anything out. Include credit cards, store cards, personal loans, medical debt, and auto loans. Mortgages are usually kept separate, but every other personal debt should go on this list.
Step 2: Order Your Debts Strictly by Interest Rate (APR)
Now that you have your list, sort your debts from top to bottom based only on the interest rate.
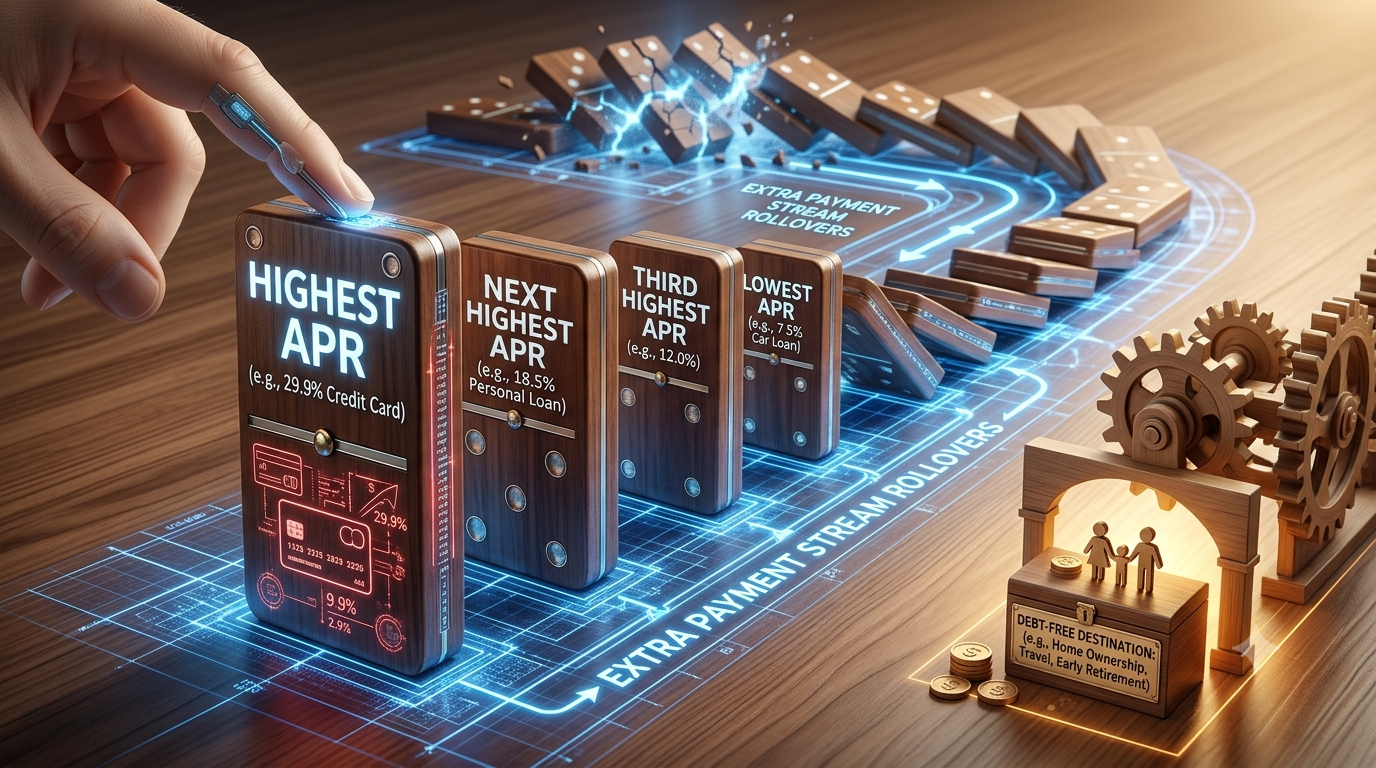
Place the debt with the highest percentage rate at the very top of your list. The debt with the second highest rate goes right underneath it. Continue sorting until your debt with the lowest interest rate sits at the very bottom.
Do not worry about which balance is bigger or smaller. Focus entirely on the APR.
-
Target #1: Highest APR (Your main target)
-
Target #2: Second Highest APR
-
Target #3: Third Highest APR
-
Target #4: Lowest APR (Your final target)
The debt at the top of this list is your financial enemy number one. It is costing you more per dollar than anything else you owe.
Step 3: Find Your Monthly Extra Payment
The debt avalanche needs fuel to move quickly. Minimum payments alone will keep you stuck in debt for decades because banks design minimums to cover mostly interest, not your principal balance.
Take a hard look at your monthly household income and expenses. Figure out the total amount you can dedicate to debt payoff each month.
Add up all the required minimum payments for all your listed debts. Subtract that sum from your total debt budget. The amount left over is your extra payment.
For example:
-
Total monthly debt budget: $800
-
Sum of all minimum payments: $550
-
Your monthly extra payment: $250
That $250 is your power tool. You will use it to break down your highest-interest debt.
Step 4: Put Your Baseline Payments on Auto-Pilot
System errors happen when life gets busy. Missing a payment adds expensive late fees and harms your credit score.
Set up automatic payments for the exact minimum amount on every debt on your list except the one at the very top.
Automating minimum payments guarantees you remain in good standing with all your lenders. It also keeps your mind clear so you can focus entirely on knocking out your top priority debt.
Step 5: Attack the Top Debt with Full Force
Now you execute the strategy. Every month, you pay:
-
The minimum payment on Target #1
-
PLUS your entire extra payment amount
You send this combined payment to Target #1 every single month without fail. Meanwhile, your automated minimum payments handle the rest of your debts in the background.
Stay focused on Target #1 until the balance reaches zero. It might take three months or it might take fourteen months depending on your balance, but every payment you make reduces the interest charged to you the following month.
Step 6: Trigger the Avalanche Rollover
This is where the magic happens. When you finally pay off Target #1, do not take that money and spend it on shopping or eating out.
Instead, take the entire payment amount you were sending to Target #1 (its minimum payment PLUS your extra cash) and add it to the minimum payment of Target #2.
Your extra payment power just grew larger. You now hit Target #2 with a much bigger monthly hammer. Because Target #2 drops even faster, you reach its zero balance in less time.
When Target #2 is gone, you roll that total combined sum into Target #3. The momentum continues to build until every account on your list is completely paid off.
Related Link: The Ultimate Guide to the Best Debt Consolidation Loans of 2026: Compare Rates, Bad Credit Options & No-Fee Lenders
A Real-World Walk through: See the Avalanche in Action
Let us look at a simple scenario to see how this works with real numbers.
Imagine Sarah has three debts:
-
Credit Card A: $3,000 balance at 24% APR (Minimum: $90)
-
Credit Card B: $1,500 balance at 18% APR (Minimum: $45)
-
Personal Loan: $5,000 balance at 10% APR (Minimum: $125)
Sarah’s total minimum payments equal $260 a month ($90 + $45 + $125). She reviews her budget and finds an extra $200 each month to throw at her debt. Her total monthly debt budget is $460.
Phase 1: Target Credit Card A (24% APR)
-
Sarah sets up auto-payments for Credit Card B ($45) and the Personal Loan ($125).
-
She pays $290 a month to Credit Card A ($90 minimum + $200 extra).
-
In about 12 months, Credit Card A is down to $0.
Phase 2: Roll Over to Credit Card B (18% APR)
-
Credit Card A is gone. Its $290 monthly payment is now freed up.
-
Sarah adds that $290 to Credit Card B’s minimum payment of $45.
-
Her new monthly payment for Credit Card B becomes $335 ($290 + $45).
-
Credit Card B vanishes in just around 4 to 5 months.
Phase 3: Roll Over to the Personal Loan (10% APR)
-
Credit Card B is gone. Sarah now has $335 freed up from her previous targets.
-
She adds $335 to the Personal Loan’s minimum payment of $125.
-
Her new monthly payment for the loan becomes $460 ($335 + $125).
-
The $5,000 loan gets wiped out in record time.
Sarah kept the exact same $460 monthly budget throughout the entire process. But by redirecting the money as debts died off, her payoff power accelerated like a snowball rolling downhill. She saved thousands of dollars in interest charges compared to paying minimums.
Common Challenges and How to Beat Them
The debt avalanche is mathematically perfect, but human beings are not machines. Here is how to handle common obstacles:
1. The Slow Start (Middle-Stage Fatigue)
Because your highest-interest debt might also have a large balance, it can take time to see your first account hit zero. This can feel discouraging.
-
The Fix: Track total interest saved rather than just account closures. Draw a simple bar chart on paper or use an online progress bar. Watching your monthly interest charges drop is a great way to stay motivated.
2. Unexpected Expenses
An emergency car repair or medical bill can disrupt your extra payments.
-
The Fix: Build a small cash safety net before starting your avalanche. Keep $1,000 in a savings account. This starter emergency fund prevents you from reaching for a credit card when life happens.
3. Adding New Debt
If you continue using credit cards while trying to pay them off, the avalanche fails.
-
The Fix: Freeze your credit cards—literally put them in a container of water in the freezer if you must, or remove the saved card numbers from online shopping websites. Use cash or a debit card for your daily living expenses.
Learn More: How to Get Out of Debt: A Step-by-Step Debt Payoff Plan for Beginners
How to Build Your Custom Debt Exit Map Today
You do not need complicated tools to start your journey. Grab a sheet of paper or open a clean document on your computer right now:
-
Write down your debts and sort them by APR from highest to lowest.
-
Calculate your total monthly minimum payments.
-
Find your extra payment amount by trimming small unnecessary expenses.
-
Set your baseline minimum payments on auto-pilot.
-
Direct every extra dollar to your highest-APR account.
The debt avalanche method takes patience at first, but math does not lie. By attacking high interest head-on, you keep your money in your bank account instead of giving it away to lenders. Take your first step today, outline your payoff order, and stick to the blueprint.